Yes, car insurance covers windshield replacement if you carry comprehensive coverage, but you'll usually pay your comprehensive deductible unless you live in a zero-deductible state or bought full glass coverage. Repairs are a different story: most big insurers waive the deductible on chip and small-crack repairs, so a fix can cost you nothing at all.
Liability-only policies don't pay for your own glass. And the details (who waives what, which number to call, which shop gets the job) change from one insurer to the next. This guide pulls it all into one place, with every phone number checked on the insurer's own website in October 2026.
Key Takeaways
- Windshield damage from rocks, hail, falling branches or vandalism falls under comprehensive coverage. Liability-only policies don't cover your own glass.
- Progressive, GEICO, Allstate and USAA all say on their own sites that they don't charge a deductible for windshield repair when you carry comprehensive.
- Florida waives the deductible for covered windshield damage, Kentucky for glass-only claims and South Carolina for automobile safety glass. Arizona and Minnesota require insurers to offer a no-deductible glass option you can buy.
- All eight insurers in our comparison work with Safelite in some way, from recommending its shops to using Safelite Solutions as a claims administrator. Allstate, GEICO, USAA and Nationwide say on their own sites that you can use another shop.
- Chips and cracks under about 6 inches can usually be repaired. Longer cracks, or damage in the driver's line of sight, usually mean replacement.
Which Part of Your Car Insurance Pays for a Windshield?
Three coverages can come into play, and which one applies depends on how the glass broke.
Comprehensive coverage
This is the one that handles almost every windshield claim. Comprehensive pays for damage that doesn't come from hitting another car: a rock thrown up by a truck, hail, a falling tree limb, vandalism, a deer. Farmers lists flying debris, severe weather, falling objects, animal strikes and vandalism as typical glass events. If the car itself hits a tree, a guardrail or another vehicle, that's usually collision, not comprehensive. Comprehensive is optional in every state, so if you only carry the legal minimum liability coverage, your windshield isn't covered.
Comprehensive has its own deductible, the amount you picked when you bought the policy. That deductible is the whole reason this topic is confusing. A $500 deductible against a windshield that costs a few hundred dollars to replace means the claim pays little or nothing.
Collision coverage
If your windshield cracked because you rear-ended someone or got hit, the glass is part of a collision claim instead, or of the at-fault driver's property damage liability claim if the other driver caused it. Farmers notes that collision may apply when the windshield needs replacing after a crash with another vehicle, and if you use your own collision coverage, your collision deductible applies. In practice, the glass becomes one line on a larger body repair estimate.
Full glass coverage (glass deductible options)
Full glass coverage is an add-on to comprehensive. You pay a bit more premium, and in return glass claims carry a lower deductible or none at all. Insurers sell it under different names:
- Farmers: "Glass Deductible Buyback" (a $100 glass deductible, $0 in some states, and $0 for chip repairs) and "Full windshield and glass coverage" (no deductible, depending on policy and state).
- USAA: a "glass waiver," which it says isn't available in all locations.
- Progressive: a "$0 deductible option for glass-only replacement claims" in certain states.
- Liberty Mutual: a glass repair deductible that can differ from your main auto deductible, shown in your online account. Terms vary by policy and state.
Whether you can buy it depends on your state and insurer. If you can, and your comprehensive deductible is $500 or higher, it's worth pricing out. Compare the add-on's premium with your deductible and what glass costs for your car; whether it pays off depends on the price and whether you ever have a covered loss.
Windshield Coverage by Insurer: 8 Companies Compared
Here's what each of the eight largest names says about glass claims on its own website. "Repair deductible waived?" means chip or small-crack repair, not full replacement. Phone numbers were checked on each insurer's site in October 2026. Your policy documents beat anything in this table, so check them if your numbers differ.
| Insurer | Repair (chip) deductible waived? | Replacement deductible | Glass network / partner | Phone / filing route |
|---|---|---|---|---|
| Progressive | Yes, with comprehensive ("we don't apply a deductible" to repairs) | Comprehensive deductible; a $0 glass replacement option is sold in certain states | Safelite AutoGlass or affiliated shops (recommended, not required) | 1-877-777-1783 (Mon to Fri, 8am to 8pm ET) |
| GEICO | Yes, with comprehensive | Comprehensive deductible unless state law or your policy says otherwise | Safelite (recommended; you can choose another shop) | (800) 510-2291 |
| State Farm | May apply; State Farm's claims page says to check your policy. Some state-specific policy endorsements say "No deductible applies to the repair of windshield glass" | Deductible may apply | Safelite Solutions LLC (third-party glass program administrator) | 888-624-4410 (Safelite Solutions); Massachusetts: 800-526-8210 |
| Allstate | Yes ("There is not a deductible for a glass repair") | Varies by state; check your policy | Safelite, via Glass Claims Express (7,200 repair shops); not required | 800-255-7828 (Allstate auto and property claims line; glass claims can also be filed online through Safelite or My Account) |
| USAA | Yes, with comprehensive | Comprehensive deductible unless you bought the glass waiver (not available everywhere) | Safelite AutoGlass ("trusted alliance"); you can pick any shop | 800-525-1790 (USAA help line listed on its glass claims page) |
| Farmers | $0 for chip repairs if you have Glass Deductible Buyback; otherwise depends on your policy | $100 with Glass Deductible Buyback ($0 in some states); otherwise your comprehensive deductible | Safelite Solutions | 1-800-435-7764 (Farmers Claims Center) |
| Nationwide | Yes, if you have glass coverage | Depends on your coverage and state | Safelite Solutions administers the optional On Your Side Glass Service | 1-800-421-3535 (say "glass only") |
| Liberty Mutual | Depends on your glass repair deductible (view it in your online account) | Varies by policy and state; check your glass deductible in your account | Safelite | 800-225-2467 (Liberty Mutual's file-a-claim line) |
A few things jump out. First, the repair waiver is common among these carriers, so a chip is worth dealing with quickly. Before you open a claim, ask a shop for a cash repair price and ask your insurer whether the call counts as a claim, since a waived deductible doesn't mean the claim stays off your record. Second, every one of them works with Safelite in some form. That's convenient, but it isn't a requirement: Allstate, GEICO, USAA and Nationwide all say on their own pages that you can use a shop of your choice, and Nationwide asks you to call before agreeing to any work. If you're weighing the in-network shop against an independent, our Safelite vs local glass shop comparison covers the trade-offs, and our breakdown of what Safelite charges with and without insurance helps when you're paying out of pocket.
Third, several insurers give you a number that rings Safelite (or a general claims line) rather than a dedicated glass desk. State Farm's number goes straight to Safelite Solutions, its third-party glass administrator. That's normal, and it's still the right number to call.
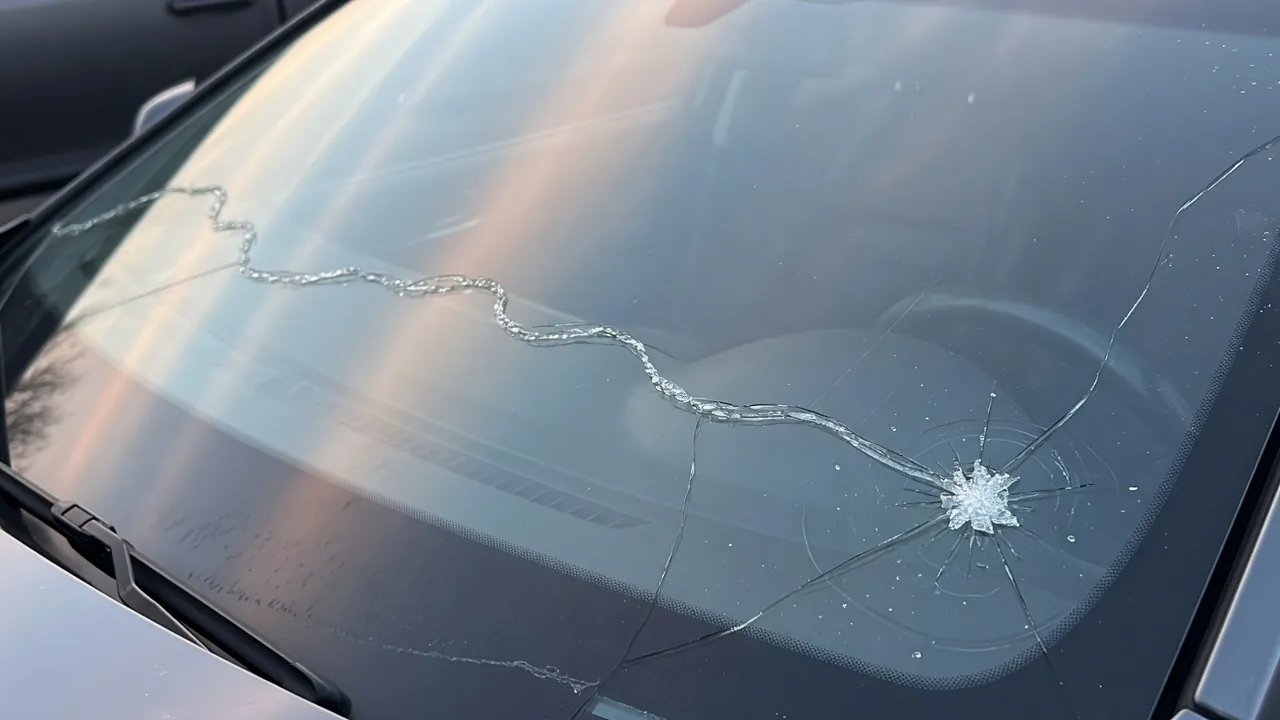
Free Windshield Replacement States: Where the Deductible Doesn't Apply
"Free windshield replacement" really means your deductible is waived by law. You still pay for comprehensive coverage in your premium. Progressive's own explainer puts it this way: in Florida, Kentucky and South Carolina, insurers can't apply a deductible to a covered windshield replacement claim if you carry comprehensive. We read the statutes ourselves, and they're not identical.
States where the deductible is waived by law
| State | Law | What it says |
|---|---|---|
| Florida | Fla. Stat. 627.7288 | The deductible on a policy with comprehensive coverage doesn't apply to damage to the windshield. Side and rear glass aren't named. |
| Kentucky | KRS 304.20-060 | Comprehensive must pay glass-only claims "without regard to any deductible." Covers windshield, door and window glass plus required lights. Since April 2, 2024 the law also counts ADAS calibration as part of glass repair and bars insurers from requiring a particular shop. |
| South Carolina | S.C. Code 38-77-280(B) | Any physical damage deductible "does not apply to automobile safety glass." |
South Carolina could change. House Bill 4817 would amend Section 38-77-280 so insurers must offer a $0 safety glass deductible rather than ban glass deductibles outright, which opens the door to a glass deductible for drivers who don't choose the $0 option. The SC House passed it on April 1, 2026, and the Senate Banking and Insurance Committee reported it favorably with an amendment on April 30, 2026. As of October 9, 2026, the SC Statehouse bill record shows no final passage or ratification. So South Carolina is still $0 today, but confirm with the South Carolina Department of Insurance or your agent before you count on it at renewal.
States where a no-deductible glass option must be offered
- Arizona (A.R.S. 20-264): insurers writing comprehensive must offer, "at the option of the insured," complete glass coverage without any deductible. You have to choose it, and it costs extra.
- Minnesota (Minn. Stat. 65B.134): same idea. Comprehensive policies must offer, at your option, full coverage for damaged safety glass with no deductible.
- Massachusetts: no mandate. The Massachusetts Division of Insurance says plainly that glass and windshield deductibles "are permitted and legal" there, and that many companies default to no glass deductible but newer quotes increasingly include one. Check your declarations page before a loss, because you can't remove a glass deductible after the damage happens.
- New York: state law (Insurance Law 3411(k), as described by the Department of Financial Services) sets minimum comprehensive and collision deductibles but carves out window glass, which "may be sold without a deductible." That permits $0 glass coverage but doesn't require every insurer to sell it, so ask your carrier.
- Connecticut: commonly listed as an optional full-glass state, where full glass coverage removes the deductible for an added premium. We couldn't open the Connecticut Insurance Department's page to confirm the exact rules, so ask your insurer or the department directly.
For a state-by-state walk-through using Progressive as the example, see our guide to zero glass deductible states.
Repair or Replace? The Thresholds Insurers Use
Whether your claim is a no-deductible repair or a deductible-bearing replacement mostly comes down to size, count and location. The insurers publish close to the same rules:
- Progressive: windshields can usually be repaired if the chip or crack is less than 6 inches long. Over 6 inches, it'll likely need replacing.
- State Farm: repairable damage is typically small breaks outside the area in front of the driver, fewer than 3 cracks, and cracks under 6 inches long or wide.
- USAA: repair works if your glass has 3 or fewer chips smaller than 6 inches. Replacement is recommended with 4 or more chips or cracks, or damage larger than 6 inches. Its FAQ also uses a simpler rule: damage smaller than a dollar bill can usually be repaired.
- Nationwide: a chip or crack measuring less than 6 inches can probably be repaired.
Location matters as much as size. A small chip directly in the driver's sight line may still be replaced, because resin repair can leave a slight distortion right where you look. Damage that reaches the edge of the glass also tends to spread and is often a replacement job. Our windshield repair vs replacement guide walks through the edge cases.
The practical takeaway: get a chip fixed quickly. A covered repair costs nothing out of pocket at most of these insurers when you carry comprehensive, is quick (GEICO says about 30 minutes in most cases, and State Farm says 20 to 30 minutes at a facility), and keeps the factory seal intact. Wait a few weeks of temperature swings and potholes, and that same chip can run into a crack that needs a full replacement and your deductible.
What Replacement Actually Costs You
Your out-of-pocket cost on a replacement is the smaller of two numbers: the replacement bill or your deductible. Progressive's own example: if the windshield costs $800 to replace and your comprehensive deductible is $100, you pay $100. Flip that around and a $500 deductible against a cheaper replacement can leave you paying nearly all of it, which is why some drivers skip the claim entirely.
Allstate gives a similar example: with a $500 comprehensive deductible and a $233 glass bill, you'd pay the whole thing yourself (unless a repair waiver, full glass coverage or a state law applies). If you're trying to figure out whether a claim is worth it, start with our windshield replacement cost guide for typical price ranges, then compare against your deductible.
OEM vs aftermarket glass
Insurers generally pay for glass of "like kind and quality," which isn't always the carmaker's own (OEM) glass. USAA says it outright: if the recommended glass isn't OEM, you can ask for OEM, but you may owe the difference. State Farm's policy language notes that replacement glass doesn't need to carry the original logo or markings. If your car has a heads-up display, acoustic glass, rain sensors or a heated wiper area, ask the shop to confirm the replacement matches those features before they order it.
ADAS camera recalibration adds cost
Many newer cars have a forward-facing camera mounted behind the windshield for lane-keeping and automatic emergency braking. After a replacement, that camera usually needs recalibration. USAA says recalibration is needed "in most cases" for cars with these features and is usually done in the same visit. It adds real money to the bill, which can push a replacement well past your deductible and make a claim more worthwhile. Kentucky's 2024 amendment now treats calibration as part of a covered glass repair. Ask whether calibration is included in the quote, and get proof it was done.
How to File a Windshield Claim, Step by Step
- Check your coverage first. Log in to your insurer's app and confirm you have comprehensive and what your comprehensive (or glass) deductible is.
- Photograph the damage with something for scale, like a coin, and note when and where it happened.
- Call the glass line or file online. Use the number in the table above, or the app. Most insurers route glass-only claims straight to their glass administrator.
- Pick a shop. You can take the insurer's network shop or one you choose. If you go outside the network, tell the insurer before work starts. Our directory can help you find auto glass repair shops near you.
- Ask about calibration and glass type before the appointment, not after.
- Inspect the work for leaks, wind noise and warning lights on the dash before you drive away.
What If You Don't Have Comprehensive Coverage?
Then your own policy won't pay for the glass, and you're paying the shop directly. You have a few options that don't involve a claim:
- Get a cash quote for repair first. If the damage is a chip or a short crack, a resin repair costs far less than a new windshield, and many shops will tell you over the phone whether it's likely repairable.
- Ask about aftermarket glass. If you're paying yourself, quality aftermarket glass is usually the cheaper route. Just confirm it supports any camera, sensor or heads-up display your car has.
- Check whether someone else is liable. If a specific, identifiable vehicle dropped a load of gravel or debris on your car, their liability coverage may be worth pursuing, though these claims are hard to prove without a plate number and photos.
- Price comprehensive at your next renewal. If you drive a newer car with expensive glass, adding comprehensive (and full glass where it's sold) can make sense on its own.
Don't ignore the damage while you decide. Nationwide notes that stresses from a cracked or improperly installed windshield can weaken the roof, especially in a rollover.
Will a Windshield Claim Raise Your Rates?
It depends on your insurer, your state and your claim history. A glass claim is a comprehensive claim, not an at-fault accident, but insurers still see it, and a string of claims in a short window can come up at renewal. If you're on the fence, ask your agent how a glass claim is rated before you file. We dig into what insurers actually do in will a windshield claim raise your insurance.
Frequently Asked Questions
Does car insurance cover a cracked windshield?
Yes, if you carry comprehensive coverage. Comprehensive pays for cracks from rocks, hail, falling objects and vandalism. You'll usually pay your comprehensive deductible on a replacement, but most large insurers, including Progressive, GEICO, Allstate and USAA, waive it for repairs.
Which states have free windshield replacement?
Florida, Kentucky and South Carolina waive the deductible by law when you have comprehensive: Florida for windshield damage only, Kentucky for glass-only claims and South Carolina for automobile safety glass. Arizona and Minnesota require insurers to offer a no-deductible glass option you can buy, and New York allows glass coverage to be sold with no deductible.
Is it worth filing an insurance claim for a windshield?
For a repair, the deductible is usually waived, but compare the cash price and think about your recent claims history before filing. For a replacement, compare the shop's quote to your deductible. If the quote is only a little above your deductible, the claim saves you little. If your car needs camera recalibration, the total often climbs enough to make a claim worthwhile.
Do I have to use Safelite for an insurance windshield claim?
Usually not. Progressive, GEICO, Allstate, USAA and Nationwide say you can choose another shop, though some want you to call first. For State Farm, Farmers and Liberty Mutual, confirm approval and payment terms before work starts. Kentucky law bars insurers from requiring a particular glass shop.
What is the auto glass claim phone number for my insurer?
For the eight largest insurers: Progressive 1-877-777-1783, GEICO (800) 510-2291, State Farm 888-624-4410, Allstate 800-255-7828, USAA 800-525-1790, Farmers 1-800-435-7764, Nationwide 1-800-421-3535 and Liberty Mutual 800-225-2467. Each was checked on the insurer's own website in October 2026. Your ID card or app will also have the right number.
Sources
- Progressive: Windshield Glass Repair and Insurance Coverage (accessed Oct 2026)
- Progressive: Which States Offer Free Windshield Replacements? (accessed Oct 2026)
- GEICO: Glass Claims Guide (accessed Oct 2026)
- GEICO: Windshield Chip Repair and Insurance Coverage (accessed Oct 2026)
- State Farm: Windshield Repair and Glass Claims (accessed Oct 2026)
- State Farm: Amendatory Endorsement 6125A (accessed Oct 2026)
- Allstate: Windshield and Glass Claims (accessed Oct 2026)
- Allstate: Claims Help (accessed Oct 2026)
- Allstate: Car Insurance for Windshield Damage (accessed Oct 2026)
- USAA: Windshield and Glass Claims (accessed Oct 2026)
- USAA: Using Your Auto Insurance (accessed Oct 2026)
- Farmers: Does Insurance Cover Windshield Replacement? (accessed Oct 2026)
- Farmers: Auto Glass Claims (accessed Oct 2026)
- Nationwide: Auto Claims, Windshield or Glass Damage (accessed Oct 2026)
- Liberty Mutual: Claims Support (accessed Oct 2026)
- Liberty Mutual: Should I File a Claim? (accessed Oct 2026)
- Florida Legislature: Fla. Stat. 627.7288 (accessed Oct 2026)
- Kentucky Legislature: KRS 304.20-060 (accessed Oct 2026)
- South Carolina Legislature: S.C. Code Title 38 Chapter 77 (Section 38-77-280) (accessed Oct 2026)
- South Carolina Legislature: H.4817 Bill History (accessed Oct 2026)
- Arizona Legislature: A.R.S. 20-264 (accessed Oct 2026)
- Minnesota Revisor of Statutes: Minn. Stat. 65B.134 (accessed Oct 2026)
- Massachusetts Division of Insurance: Understanding Whether Auto Coverage Pays for Damage to Your Windshield (accessed Oct 2026)
- New York DFS: OGC Opinion 10-06-08, Deductibles for Automobile Physical Damage Insurance Policies (accessed Oct 2026)